Whether you are relocating across the country for a new career, upsizing for a growing family, or finally breaking into your local housing market, affordability and monthly cash flow are top of mind for Canadian homebuyers.
Every week, our team at Merge Mortgage Group works with buyers across British Columbia, Alberta, Saskatchewan, and Ontario to navigate shifting real estate markets. And thanks to the recent federal Budget 2026 announcements, financing your next home whether across provincial lines or right in your own backyard could soon become much more flexible.
The federal government has proposed expanding 30-year amortizations and raising price caps for optionally insured mortgages. If you are looking to buy a new build, purchase your first home, or relocate to a different Canadian market, understanding how to leverage these rules is critical. Here is our breakdown of what these changes mean for Canadian buyers.
More Flexibility Across Diverse Canadian Markets
Canadian real estate isn’t one-size-fits-all. A $1.3 million family home in the Greater Toronto Area or Metro Vancouver comes with very different financing needs than a $450,000 detached home in Calgary, Edmonton, Saskatoon, or Regina.
Budget 2026 directly addresses both ends of that spectrum by focusing on optionally insured (insurable) mortgages which typically apply when a buyer puts 20% or more down and the lender chooses to insure the loan behind the scenes to access lower, competitive interest rates.
Under the proposed changes:
Higher Property-Value Limits: The price cap for optional mortgage insurance is increasing from $1 million to $1.5 million. For buyers in higher-priced markets like BC and Ontario putting 20% down, this opens the door to lower "insurable" mortgage rates that were previously out of reach above $1 million.
Extended 30-Year Amortizations: The maximum repayment period for these optionally insured mortgages stretches from 25 years to 30 years, giving eligible buyers across every province more breathing room in their monthly budget.
Who Qualifies for the 30-Year Extension?
To access the proposed 30-year amortization on an optionally insured mortgage, you must meet one of two criteria:
You are buying new construction: If you are purchasing a newly built property from a suburban detached home in the Prairies to a new condo or townhome in BC or Ontario you qualify for the 30-year amortization.
You are a first-time homebuyer: If at least one borrower on the application is buying their first home, you can access the 30-year option on resale properties as well.
The Financial Impact: Lower Monthly Payments, Better Cash Flow
Stretching your amortization from 25 to 30 years lowers your required monthly mortgage payment, freeing up cash flow for renovations, investments, childcare, or relocation expenses.
Here is a hypothetical look at how a 30-year amortization impacts monthly payments across two different Canadian price points (assuming a 4.5% interest rate):
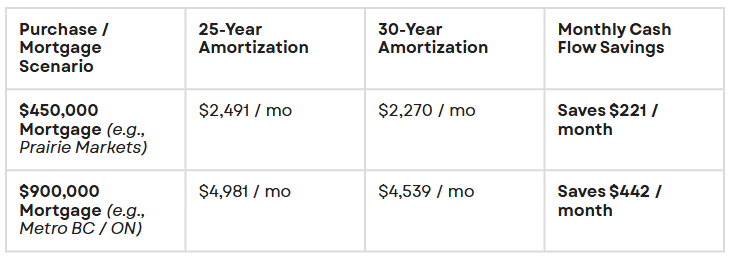
While a 30-year schedule does mean paying more total interest if you carry the loan for the full three decades, the immediate monthly savings can make transitioning into a new home or to a new province, significantly more comfortable.
3 Smart Strategies for Today’s Buyers
Whether you are moving across provinces or staying local, here is how to position yourself to take advantage of the evolving mortgage landscape:
Consider New Construction: Because the 30-year amortization applies to all eligible new builds (not just first-time buyers), purchasing a newly constructed home is a great way to keep monthly payments manageable while avoiding immediate repair or renovation costs.
Factor in Total Cost of Ownership: Every province has its own financial nuances, from land transfer taxes and provincial sales taxes to property tax rates and utility costs. Looking at the full monthly picture helps ensure your new mortgage fits comfortably alongside your day-to-day lifestyle.
Use Prepayment Privileges to Stay Ahead: A 30-year amortization doesn't mean you have to take 30 years to pay off your home. You can lock in the security of a lower required monthly payment today, and as your income grows or your relocation settles, use your mortgage's prepayment privileges to pay down the principal faster without penalty.
Let’s Map Out Your Next Move
Whether you are buying your first condo in Vancouver, upgrading to a family home in Toronto, investing in Edmonton, or putting down roots in Saskatoon, Merge Mortgage Group has local expertise across British Columbia, Alberta, Saskatchewan, and Ontario. We specialize in helping Canadians compare lenders, navigate inter-provincial moves, and structure mortgages for long-term wealth.
Note: Budget 2026 mortgage measures are subject to federal legislative and regulatory rollout timelines.
Ready to see how current and upcoming mortgage rules apply to your homebuying plans? Let’s chat. Visit us at mergemortgage.ca to connect with a broker in your province today!
📍Serving Alberta, BC, Ontario and SK
🌐 mergemortgage.ca